What should I do about the 2026 California FAIR Plan rate increase?
Read the actual renewal, compare the full FAIR Plan and companion-policy cost, check coverage gaps, and explore available alternatives before replacing anything.
Insights
Start with the question you are trying to solve, then explore practical guides about coverage, quotes, contracts, premium changes, renewals, and growing a business.
Business insurance help
You do not need to know the name of a policy before asking for help. Choose the situation that sounds closest to yours.
Clear answers for homeowners reviewing a FAIR Plan renewal, companion coverage, or a non-renewal notice.
Read the actual renewal, compare the full FAIR Plan and companion-policy cost, check coverage gaps, and explore available alternatives before replacing anything.
The FAIR Plan provides basic named-peril property coverage. A separate DIC policy may add coverage such as water damage, theft, and liability, subject to its terms.
Confirm the reason and deadline, ask about mitigation, gather property records, shop the voluntary market, and consider the FAIR Plan only when regular coverage is not reasonably available.
Begin with how the business operates, what it needs to protect, and what is changing.
Start with employees, vehicles, property, liability created by the work, and obligations in leases or customer contracts.
Build the review around what the company will do on its first day—before hiring, leasing space, buying vehicles, or beginning work.
Understand what information matters and how to compare options beyond the total price.
Compare covered operations, limits, deductibles, exclusions, endorsements, insurer requirements, and service—not only premium.
Prepare a clear business description, claims reports, payroll, vehicles, drivers, property values, and contract requirements.
Use business changes and renewal events as a prompt to make sure the policy still describes the operation.
Growth, claims, vehicles, payroll, property values, coverage changes, insurer rates, and market conditions can all affect renewal.
Confirm operations, exposures, claims, schedules, contracts, and business changes before the final renewal proposal arrives.
Confirm the reason and deadline, gather loss runs and current records, address known concerns, and begin exploring alternatives.
New employees, vehicles, locations, equipment, services, contracts, ownership, claims, or states can trigger a review.
Latest articles
Compare independent agents and direct insurers based on advice, available options, policy terms, service, and total cost.
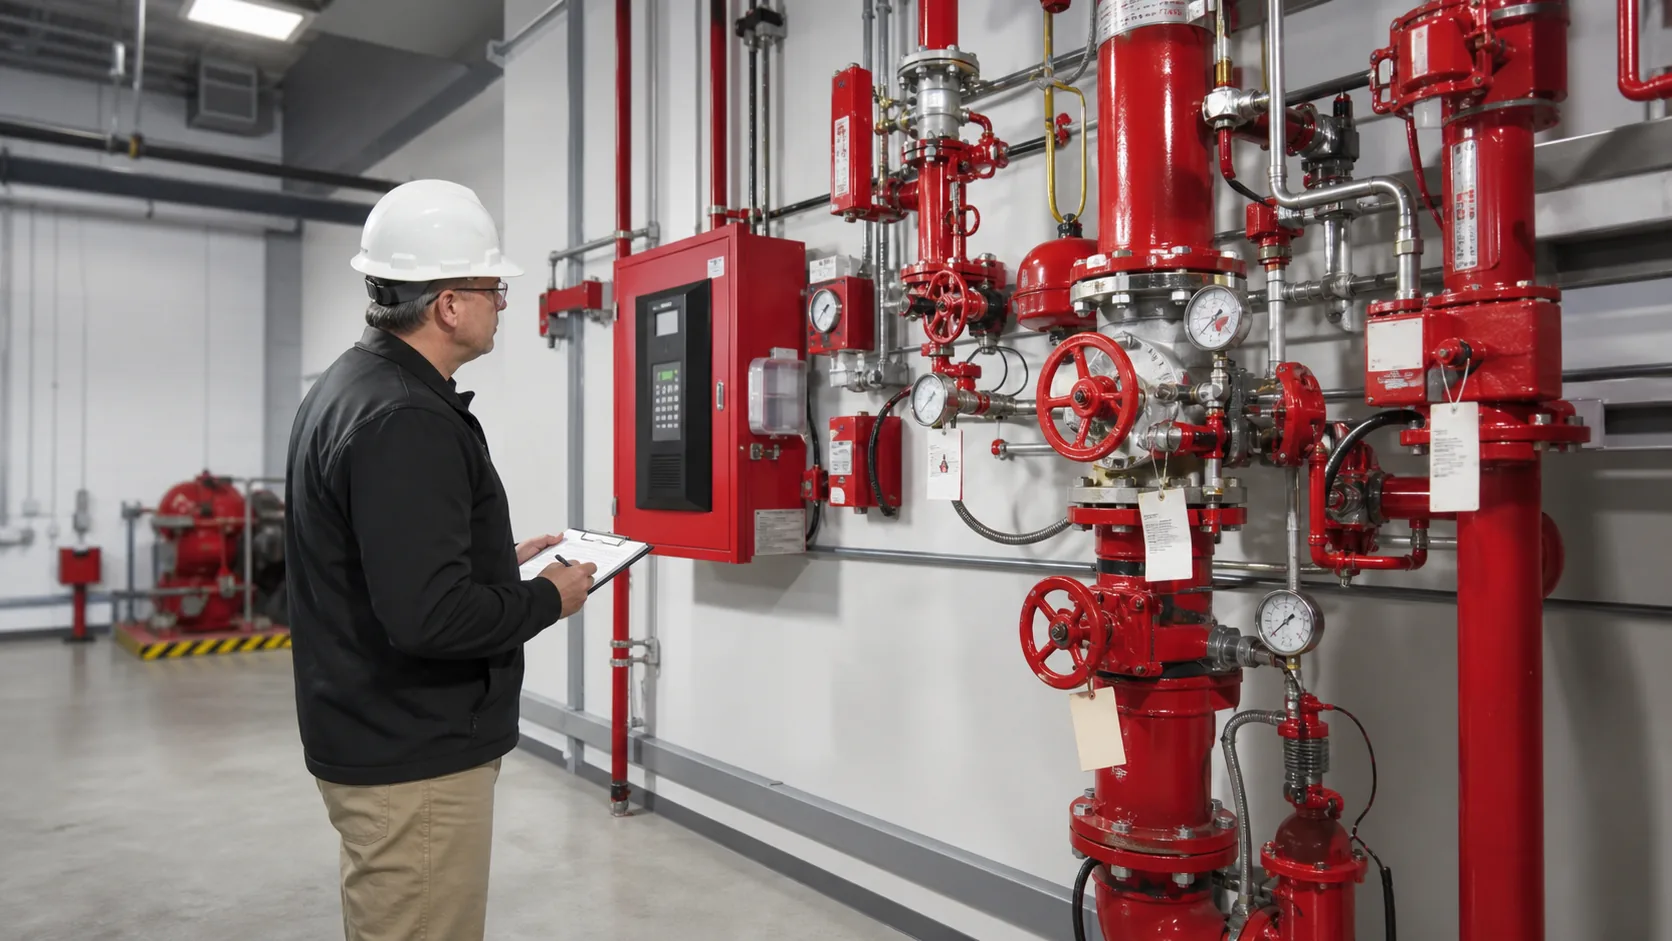
Learn how property-policy requirements for sprinklers, alarms, and other safeguards can affect maintenance, impairment notice, and a fire-loss claim.
A plain-language guide to what the MCS-90 does, when federal financial-responsibility rules may apply, and why the underlying policy still matters.
Understand four common contract requests—certificate holder, additional insured, primary and noncontributory, and waiver of subrogation—before sending proof.
Protect your restaurant's kitchen, people, equipment, inventory, customers, alcohol service, and delivery activity with coverage built around daily operations.
Protect payroll, finished work, tools, vehicles, contracts, and subcontractor relationships with an insurance review built around the way your construction company operates.
Compare workers' compensation requirements, job classifications, payroll, audits, owner treatment, and claims history across BLIS's five licensed states.
Turn a contract's insurance section into a practical checklist for limits, certificates, additional insured status, payment order, and recovery rights.
Protect the parts of your healthcare practice malpractice insurance does not address, including your office, equipment, data, employees, and premises.
Learn how to protect your cleaning company from damaged client property, missing keys, employee theft, workplace injuries, and contract problems.
Learn which operating details can affect truck insurance price—and why FMCSA authority, filings, and legal limits belong on a separate checklist.
Use this field-by-field guide to check a certificate of insurance, spot missing information, and know when to ask for the policy endorsement behind it.
A practical guide to checking policies, limits, endorsements, driver coverage, and proof before a last-mile delivery contract starts.
Protect the buildings, machinery, seasonal workforce, vehicles, products, and visitor activity that keep a commercial farm operating.
Review a marketplace insurance request alongside product and importer roles, peak inventory at 3PL sites, transit responsibility, and storefront data risks.
Gather the building values, system updates, occupancy details, claims history, and fire-protection information owners need for a smoother property insurance review.
Learn how to protect a growing manufacturing business from product injury claims, distributor requirements, coverage gaps, and the direct cost of a recall.
A practical board guide to master-policy boundaries, building values, D&O, crime coverage, lender requirements, and the 90-day renewal timeline.
Get started
Tell us what changed, what you need to protect, or what deadline you are facing. We will review the details and explain the available next steps in plain language.